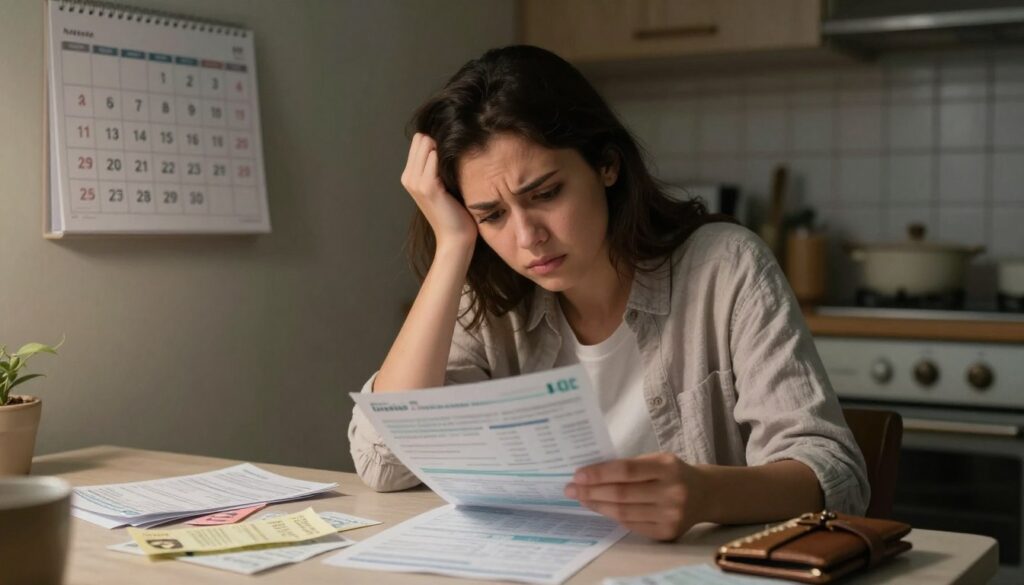
One in four households faces the stress of seeing every dollar leave the account before the next payday. The Bank of America Institute reports that about 25% of families are in this exact spot.
You are not alone. Many Americans feel trapped in a cycle where bills and basic needs eat up income. This section shows a simple, practical way to begin changing that pattern.
Intentional steps can free up money and peace of mind. It takes small moves over time, but each choice reclaims control of your finances. Start with clear tracking and one manageable goal. For practical saving tips and next steps, see a helpful guide at smart saving tips.
Key Takeaways
- Know you’re not alone: 25% of households face this issue.
- Track income and spending to find quick wins.
- Small changes add up over time.
- Break the cycle with one clear goal.
- Use a proven plan for lasting security.
Understanding the Paycheck to Paycheck Cycle
Emotional triggers and routine choices quietly keep good earners trapped in a repeating paycheck cycle. The psychology of spending often favors instant reward over future security. That makes it easy for impulse buys and small conveniences to add up fast.
Lifestyle inflation is a common culprit. When income rises, many adjust their wants, not just needs. Over time, higher pay can simply feed higher monthly costs and leave little left for saving.
The Psychology of Spending
Impulse purchases and emotional buys break budgets. They create short-term pleasure but long-term friction in your finances. Recognizing these triggers helps you choose differently.
Identifying Lifestyle Inflation
Track recurring small costs. Subscriptions, dining out, and upgraded services quietly extend the paycheck paycheck pattern. A simple audit reveals where extra income disappears.
- Watch small, repeating charges: they shape the paycheck cycle.
- Ask why you spend: emotional needs often drive purchases.
- Swap one habit: redirect an extra expense into savings.
For practical steps that turn awareness into action, check these saving tips.
How to Stop Living Paycheck to Paycheck with a Budget
A clear budget makes each dollar work toward a goal, not vanish unnoticed. Use a simple plan that assigns every dollar a purpose. A zero-based budget gives that structure and keeps money from slipping away.
Try a tool that organizes your monthly income. The EveryDollar app helps users find extra margin in minutes by labeling each dollar. When you see where money flows, you can cut waste and protect savings.
Without a budget, your finances feel like driving without a map. A steady budgeting habit uncovers hidden charges, calms stress, and brings control back into your account.
“Giving every dollar a job removes guesswork and builds lasting financial confidence.”
- Zero-based budgeting: assign every dollar so nothing is left idle.
- Track monthly spending: spot small leaks before they grow.
- Use tools: apps reveal quick margin and make the plan easy to follow.
| Method | Benefit | Example |
|---|---|---|
| Zero-based budget | Every dollar has a job | Monthly bill coverage, savings goal |
| App tracking | Immediate visibility of money | Find extra margin in minutes |
| Consistent review | Fewer surprises in account | Adjust each month for better results |
For clear saving steps and practical tips, see the best way to save money guide.
Prioritizing Essential Expenses and the Four Walls
Prioritizing essentials gives the budget a simple backbone that keeps families secure. The Four Walls are basic: food, utilities, shelter, and transportation. Place these first when you assign each dollar in a month.
Managing Monthly Bills
When you make the Four Walls nonnegotiable, paying monthly bills becomes clearer. Start by listing every expense and mark which costs protect daily life.
Allocate enough from each paycheck to cover food, electricity, rent or mortgage, and a reliable car for work. This reduces last-minute panic and keeps basic needs stable.
- Secure core payments: cover food and shelter first.
- Order expenses: rank bills by importance so the paycheck meets essentials.
- Lower utility costs: call providers and ask for lower rates or assistance programs.
| Priority | What it covers | Quick action |
|---|---|---|
| Food | Groceries and basic meals | Budget weekly shopping, use meal plans |
| Utilities | Electricity, water, heat | Negotiate rates, apply energy-saving steps |
| Shelter | Rent or mortgage | Set automatic payments, review refinancing options |
| Transportation | Car payments, gas, insurance | Maintain vehicle, compare insurance rates |
Strategies for Eliminating High-Interest Debt
Tackling expensive debt is the fastest way to free cash for saving and real progress. High-interest balances, especially on a credit card, eat into every paycheck and slow your plans.
Stop adding new purchases to revolving accounts and focus extra money on the smallest balance first. The debt snowball method builds momentum by creating quick wins.
- Freeze new charges: avoid using a card until balances fall.
- Prioritize extra payments: target the smallest debt while making minimums on others.
- Plan for emergencies: set a simple backup so you won’t rely on credit during a crisis.
“Paying down one account at a time turns dozens of payments into rising monthly savings.”
| Action | Benefit | Result |
|---|---|---|
| Debt snowball | Quick wins | More money freed each month |
| Stop new card use | Lower interest growth | Faster payoff |
| Emergency plan | Avoid new debt | Stable progress |
As balances shrink, that recovered money funds savings and goals. For more saving ideas that pair well with a payoff plan, see smart saving steps.
Boosting Your Income Through Side Hustles
A few paid hours each week can turn spare skills into meaningful extra money. Start by listing what you do well and what others will pay for. Simple offerings often beat complicated plans.
Leverage existing skills like babysitting, house cleaning, tutoring, or driving for Uber to add steady income. These gigs use strengths you already own and need little startup cost.
Leveraging Your Existing Skills
Choose work you can schedule around your main job. That keeps energy high and avoids burnout. Dedicate a few evenings or a weekend block for consistent results.
Exploring the Gig Economy
Gig platforms let you pick jobs that fit your life. Many people find steady extra money by delivering food, performing small repairs, or offering rides.
“By treating side work like a short-term project, you can free cash for debt and build savings faster.”
- Start small and test demand for one service.
- Track hours and pay each week so effort maps to results.
- Reinvest early gains into debt payoff or an emergency fund.
| Option | Typical weekly hours | Expected benefit |
|---|---|---|
| Babysitting / Tutoring | 4–10 | Quick extra money, flexible scheduling |
| Rideshare / Delivery | 5–15 | Immediate pay, scalable with demand |
| Cleaning / Handyman | 3–8 | Repeat clients, steady supplemental income |
Many people have turned a side hustle into full-time work. If you need ideas that start with no cash, check this guide on zero-upfront side hustles.
Building Financial Security for the Future
An emergency cushion protects your progress and keeps one setback from becoming a crisis. Most people can reach a $1,000 emergency fund in about 30 days by trimming nonessential monthly costs. That first buffer is powerful.
Aim next for three to six months of expenses parked in a high-yield savings account. This level of savings helps you avoid new debt when an unexpected emergency arrives.
Set clear goals and automate contributions. When your bank moves money into savings on payday, you pay yourself first and reduce temptation for impulse purchases.
- Pick a monthly savings target and add it to your budget.
- Use a dedicated savings account so the funds are easy to track.
- Celebrate milestones—each month builds confidence and habit.
“When a plan meets habit, the account grows and stress shrinks.”
For a practical guideline on setting contribution levels, see this short guide on how much of your paycheck should you.
Conclusion: Achieving Lasting Financial Freedom
Consistent wins, cut the power of debt and free cash for what matters. Small habits—simple budgeting, ranked essentials, and steady savings—build real momentum.
Prioritize essentials each month and attack high-interest debt so payments shrink and breathing room grows. Add extra income when you can and watch progress accelerate.
Keep spending in check, set clear goals, and protect an emergency fund. When you need practical steps for the next move, see this start saving guide.
With a clear plan and steady action, you can break the paycheck cycle and hold lasting control of your money and future.
FAQ
What is the paycheck-to-paycheck cycle and why does it happen?
How can I create a simple budget that actually works?
What are the “four walls” of spending I should prioritize?
Which debt should I tackle first: credit cards or student loans?
How much should I keep in an emergency fund?
Can a side hustle really make a difference?
How do I stop lifestyle inflation after a raise?
What are practical ways to cut monthly expenses fast?
How should I use credit cards while rebuilding savings?
What financial habits prevent falling back into the cycle?
Are small savings efforts worth it if income is low?
How do I pick the best bank account for an emergency fund?
When should I consult a financial advisor?


